Costco Wholesale Corporation operates a membership warehouse model built on an unusual strategic choice: it deliberately limits merchandise markups and assortment breadth in order to maximize member value, shopping frequency and inventory velocity. In fiscal 2025, Costco generated $275.24 billion of total revenue, including $269.91 billion of net sales and $5.32 billion of membership fees, from 914 warehouses worldwide.
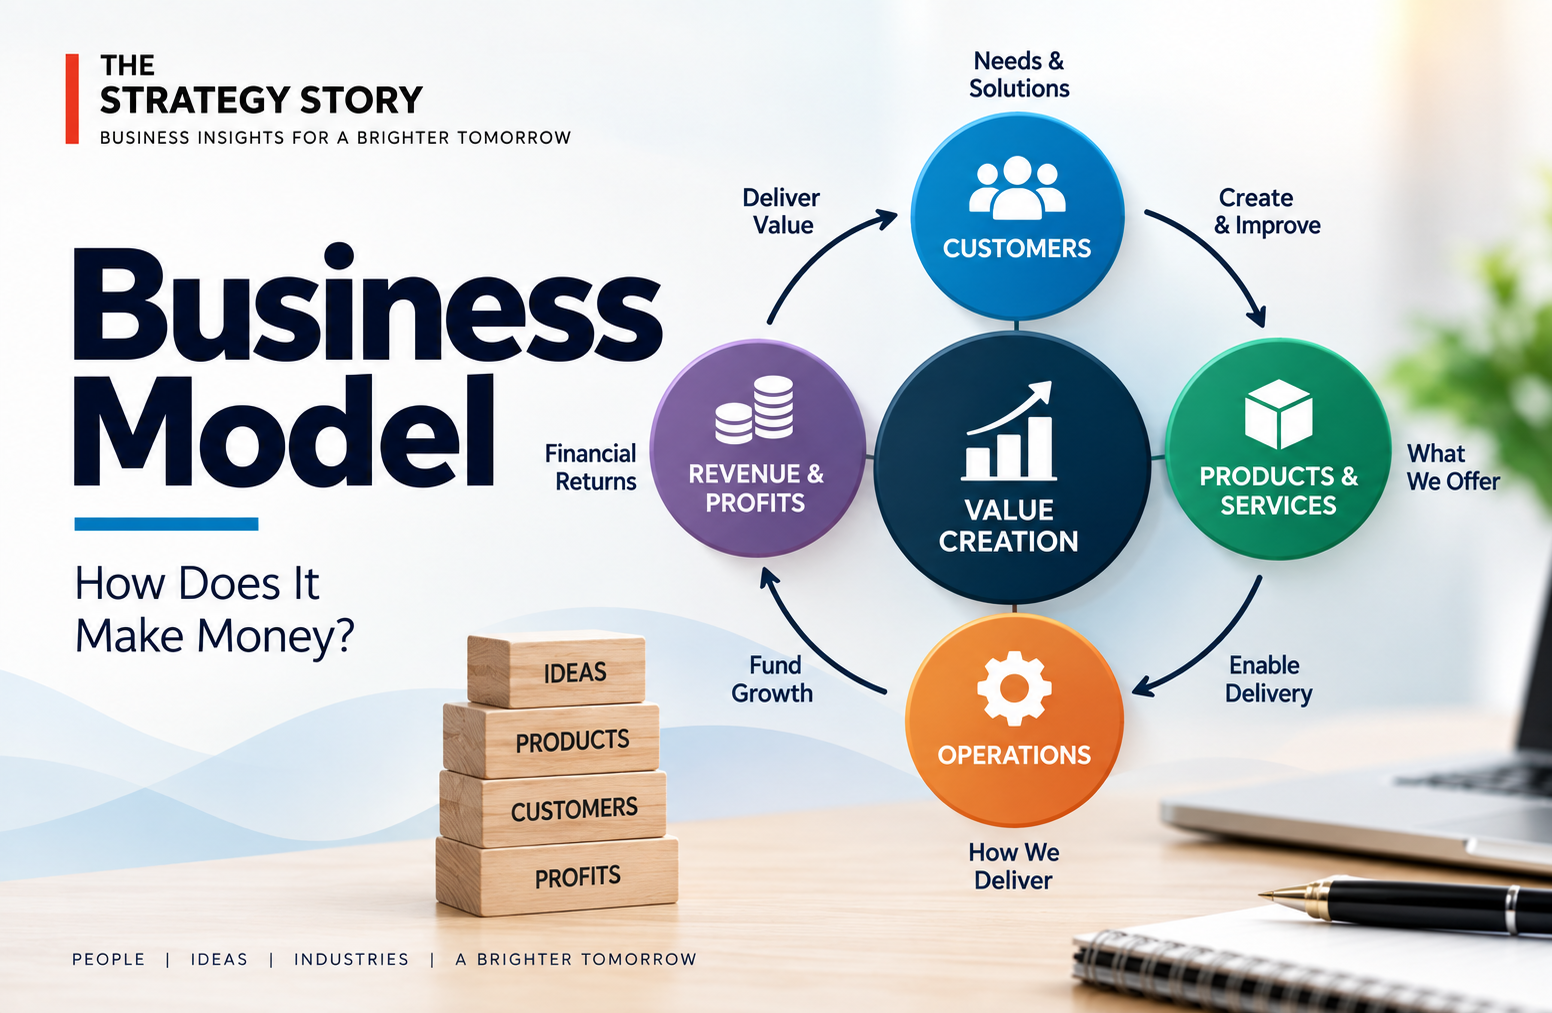
The model is more sophisticated than “buy in bulk and sell cheaply.” Costco uses low merchandise margins to create a compelling reason to pay for membership; membership creates recurring fee income and a known customer base; high traffic concentrates enormous purchasing volume on a limited number of SKUs; that purchasing scale supports lower prices; and low prices reinforce renewal. In 2025, net sales grew 8%, membership fees 10% and net income 10%—evidence that the flywheel can scale without requiring higher merchandise markups.
1. Industry Problem Costco Solves
Retail customers face an abundance problem. Conventional supermarkets, mass merchants and e-commerce platforms compete with enormous assortments, promotions and price points, leaving consumers to determine whether they are receiving genuine value. Retailers simultaneously face a margin problem: broad assortments create inventory complexity, handling costs and slower turns.
Costco attacks both problems by reducing choice and increasing trust. Rather than stock many variants of the same product, it concentrates demand on selected national brands and Kirkland Signature. The economic consequence is important: fewer SKUs can generate much higher unit volume per item, strengthening purchasing leverage while simplifying replenishment and warehouse operations.
The second customer problem is the recurring cost of household consumption. Food, fuel, pharmacy, household supplies and other categories are purchased repeatedly. Costco turns the annual membership fee into a promise that repeated shopping should generate enough savings and utility to justify the fee. Renewal rates of 92.3% in the U.S. and Canada and 89.8% worldwide suggest that most members continue to perceive that value.
For the strategic choices reinforcing this model, read our Costco Business Strategy 2026.
2. Costco’s Unique Solution
Costco’s solution is a closed-loop membership ecosystem built around price credibility. The company operates no-frills warehouses, limits assortment, purchases at enormous scale and turns inventory rapidly. It then layers gasoline, pharmacy, optical, food courts, hearing aids and tire installation around the core merchandise offer to increase the number of reasons a member uses Costco.
The limited-assortment model is strategically powerful because it changes supplier economics. When Costco selects an item, demand can be concentrated across hundreds of warehouses rather than fragmented among many competing SKUs. This can improve buying power while making each merchandising decision unusually consequential. Costco’s model therefore reduces assortment complexity but raises the importance of item selection.
Kirkland Signature adds a proprietary layer. Costco states that Kirkland products are generally priced below national brands and generally earn higher margins. That creates a rare win-win: a product can strengthen the member’s perception of savings while improving Costco’s unit economics. Because Kirkland is exclusive, it also makes direct price comparison harder and gives members a reason to return.
Ancillary services deepen the ecosystem. Costco operated 747 gas stations in 2025, with gasoline representing roughly 10% of net sales. Fuel can have modest or volatile margin economics, but competitively priced gasoline can increase visit frequency and reinforce the membership proposition. The relevant economics therefore extend beyond the profit of the fuel transaction itself.
For the model’s structural strengths and vulnerabilities, see our Costco SWOT Analysis 2026.
3. Costco Business Model
Membership creates recurring economics
Members pay annual fees for access to Costco’s warehouses and digital channels. Membership fee revenue reached $5.32 billion in 2025, up 10% from $4.83 billion. The fee increase effective September 2024 contributed about 40% of membership-income growth, while member sign-ups supplied another growth engine.
Low margins create the value proposition
Costco generated $30.03 billion of gross margin on $269.91 billion of net sales, equivalent to an 11.12% gross-margin rate. That thin margin is not a weakness accidentally tolerated by management; it is a strategic design choice. Lower markups strengthen perceived value, which supports traffic and renewal.
High volume and rapid inventory turnover create efficiency
Large sales volumes allow Costco to spread warehouse and corporate costs across a huge revenue base. Comparable sales increased 6% in 2025, driven by approximately 5% higher shopping frequency and 1% higher average ticket. Frequency doing most of the work is strategically encouraging because it indicates deeper recurring usage rather than growth dependent primarily on inflation or larger baskets.
Kirkland improves differentiation and economics
Private label allows Costco to offer differentiated products while generally earning better margins than on national brands. Increasing Kirkland penetration can therefore offset some pressure inherent in the low-markup model without requiring broad-based price increases.
Physical warehouses remain the productivity engine
Costco ended 2025 with 914 warehouses and added 24 net new locations during the year. The network contained approximately 134.7 million square feet of operating floor space. Warehouses function as high-throughput retail assets rather than presentation-heavy stores, keeping the model focused on volume and operating efficiency.
Digital expands convenience, but with different economics
E-commerce represented about 7% of net sales and comparable e-commerce sales increased 16%. Digital growth is strategically useful but not economically identical to warehouse growth: Costco states that e-commerce carries a lower gross-margin percentage. The goal is therefore omnichannel membership utility, not replacing warehouses with delivery.
For the external forces influencing these economics, read our Costco PESTEL Analysis 2026.
4. How Does Costco Make Money?
Merchandise sales
Net sales were $269.91 billion in fiscal 2025, up $20.29 billion or 8%. Comparable sales contributed approximately $14.79 billion of that increase, meaning roughly 73% of incremental net sales came from existing comparable operations rather than simply adding warehouses. That is an important quality-of-growth signal: mature assets are still becoming more productive.
Membership fees
Membership fees were only about 1.9% of total revenue, yet their strategic importance is far larger than their revenue share. The $5.32 billion recurring stream allows Costco to optimize merchandise pricing for member value rather than maximizing product margin. High renewal creates visibility and makes the member relationship itself an economic asset.
Gasoline and ancillary businesses
Gasoline accounted for roughly 10% of net sales. An 8% decline in average price per gallon reduced 2025 sales by $2.33 billion even though gallons sold increased about 2%. This demonstrates why Costco’s headline revenue can understate underlying activity: commodity-price deflation can reduce reported sales while customer volume rises.
E-commerce and other businesses
E-commerce, business centers, travel and related operations broaden the occasions Costco can monetize. The 16% comparable e-commerce growth rate was more than twice the company’s 6% reported comparable-sales growth, indicating that digital convenience is becoming a meaningful incremental layer on top of the warehouse model.
5. Costco Financial Analysis
Underlying sales momentum was stronger than headline growth
Reported comparable sales increased 6%, but comparable sales excluding gasoline-price and foreign-currency effects increased 8%. Currency movements reduced net sales by approximately $1.94 billion, while lower gasoline prices reduced sales by $2.33 billion. The gap shows why Costco should be analyzed through traffic and underlying comparable activity rather than revenue alone.
Frequency is the strongest operating signal
Shopping frequency increased about 5% while average ticket rose only about 1%. That mix matters. Growth driven by visits suggests Costco is becoming more embedded in members’ routines; growth driven mainly by ticket could instead reflect inflation. More frequent interactions also increase the opportunity to monetize ancillary services and reinforce renewal.
Gross margin improved without abandoning the value model
Gross margin increased to 11.12% from 10.92%, a 20-basis-point improvement. Excluding gasoline-price deflation, improvement was 11 basis points. On a $269.91 billion sales base, even small basis-point movements can be economically meaningful, illustrating the power—and sensitivity—of Costco’s scale.
Profit and cash grew faster than the store base
Net income increased 10% to $8.10 billion while operating cash flow rose to $13.34 billion from $11.34 billion, an increase of roughly 18%. With only 24 net new warehouses on a base of roughly 890 at the prior year-end, location count grew by less than 3%. Earnings and cash therefore expanded much faster than physical footprint, demonstrating productivity from comparable sales, membership growth and operating leverage.
Membership is economically small but strategically disproportionate
Membership fees of $5.32 billion compare with net income of $8.10 billion. The figures are not directly comparable because membership revenue has associated costs and merchandise operations generate profit too, but the scale illustrates why renewal is so strategically important. A revenue stream representing less than 2% of total revenue is central to the economics of a company producing more than $8 billion of annual net income.
6. Future of Costco’s Business Model
Costco’s future growth can come from four reinforcing sources: more members, more spending from existing members, more warehouses and more digital engagement. The attractive feature is that none requires changing the core proposition. Twenty-four net new warehouses expanded physical reach in 2025, while 16% e-commerce comparable growth expanded digital usage.
International expansion provides a long runway but will likely dilute some headline loyalty metrics while cohorts mature. Costco had 629 warehouses in the U.S. and Puerto Rico, 110 in Canada and 175 across other international markets. Worldwide renewal at 89.8% already trails the 92.3% U.S./Canada rate partly because newer international and online-acquired cohorts renew at lower rates.
Kirkland is another compounding lever. Greater private-label penetration can simultaneously differentiate Costco, lower member prices and improve margins. The strategic risk is concentration of trust: as Kirkland becomes more important, a major quality or supply failure would affect not merely one product but Costco’s own brand credibility.
The digital challenge is more nuanced. E-commerce is growing rapidly but carries lower gross-margin economics. Costco should therefore resist copying conventional online retail models that optimize for assortment and delivery at any cost. Digital works best when it makes the membership ecosystem more convenient while preserving the warehouse network’s high-volume economics.
The deepest insight is that Costco does not maximize the economics of individual transactions. It maximizes the economics of a long-lived member relationship. Low prices can sacrifice margin today to strengthen traffic and renewal tomorrow; ancillary businesses can create value through frequency beyond standalone profit; and membership fees monetize trust accumulated across the entire system. As long as Costco protects that trust, scale makes the flywheel progressively harder for conventional retailers to replicate.
Source: Costco Wholesale Corporation, FY2025 Annual Report / Form 10-K.