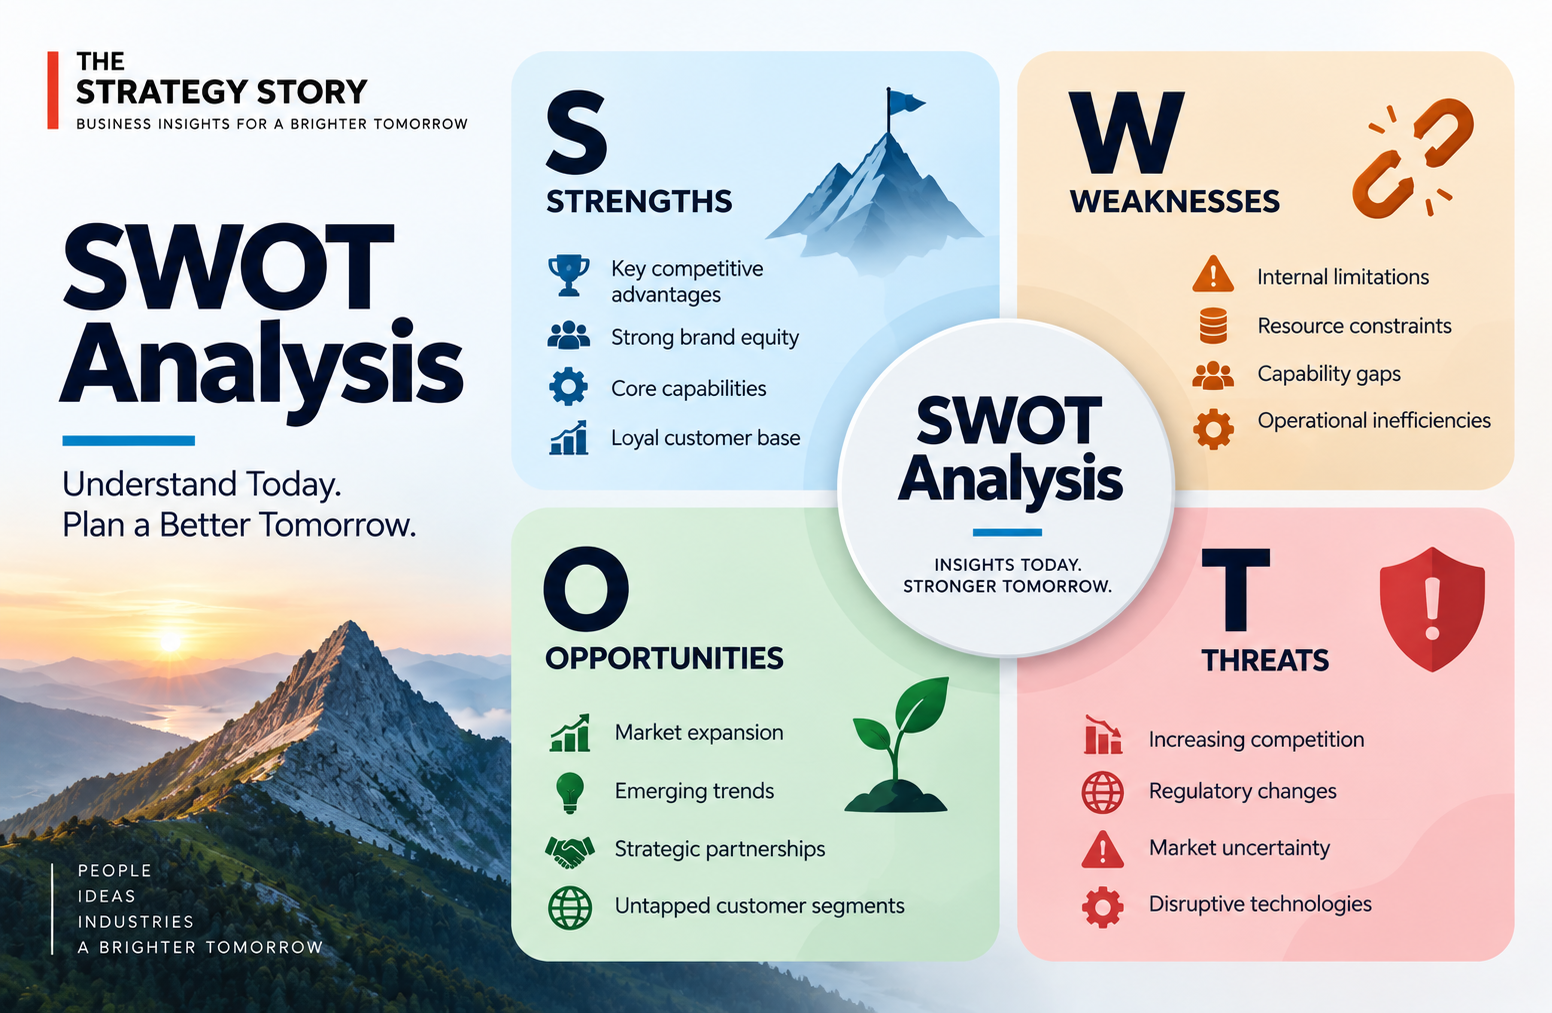
Costco entered 2026 with strong operating momentum. Fiscal 2025 net sales increased 8% to $269.91 billion, membership fee revenue increased 10% to $5.32 billion, and net income increased 10% to $8.10 billion. Its membership model, low-price positioning and global warehouse network create substantial strengths, while thin merchandise margins, concentration in North America and operating complexity create vulnerabilities.
For how these advantages combine economically, read our Costco Business Model 2026.
Strengths
1. Highly recurring membership model
Membership is integral to Costco’s profitability. Fee revenue reached $5.32 billion in 2025, up 10%, while renewal rates were 92.3% in the U.S. and Canada and 89.8% worldwide. Recurring fees support profitability and reinforce loyalty, allowing Costco to maintain a low-price merchandise strategy while monetizing the long-term member relationship.
2. Powerful scale and sales productivity
Costco generated $269.91 billion of net sales through 914 warehouses and e-commerce operations. Comparable sales increased 6%, driven by approximately 5% higher shopping frequency and 1% higher average ticket. High volumes strengthen purchasing scale and help Costco leverage warehouse and corporate operating expenses across a very large revenue base.
3. Kirkland Signature differentiation
Costco states that Kirkland Signature products are high quality, generally priced below national brands and generally earn higher margins. Private label therefore supports both customer value and economics. Exclusive products also differentiate Costco’s assortment from competitors and can deepen member loyalty because equivalent Kirkland-branded items are not available from rival retailers.
4. Strong ancillary ecosystem
Gasoline, pharmacy, optical, food courts, hearing aids and tire installation broaden the reasons members visit Costco. The company operated 747 gas stations at fiscal year-end, and gasoline represented approximately 10% of total net sales. These services can increase shopping frequency and make the annual membership more useful across multiple household needs.
5. Strong cash generation and profitable growth
Net income rose 10% to $8.10 billion in 2025, while operating cash flow increased to $13.34 billion from $11.34 billion. Gross margin also improved to 11.12% of net sales. This cash generation gives Costco capacity to open warehouses, invest in logistics and digital capabilities, maintain facilities and return capital to shareholders.
For the strategic choices Costco is making to compound its membership flywheel, see our Costco Business Strategy 2026.
Weaknesses
1. Structurally thin merchandise margins
Costco intentionally operates with low merchandise markups. Gross margin was $30.03 billion on $269.91 billion of net sales, equal to 11.12%. This supports member value but leaves less room to absorb persistent cost shocks. Small changes in merchandise costs, wages, shrink, logistics or pricing can therefore have meaningful effects on operating profitability.
2. Heavy dependence on North America
Of Costco’s 914 warehouses at August 31, 2025, 629 were in the U.S. and Puerto Rico and another 110 were in Canada. The U.S. and Canada therefore represent most of the physical network. This concentration gives Costco scale but also increases exposure to North American consumer conditions, regulation and competitive dynamics.
3. E-commerce has lower gross-margin economics
E-commerce is growing rapidly, with comparable sales up 16% in 2025, but Costco states that its e-commerce business has a lower gross-margin percentage than warehouse operations. As members demand more digital convenience and delivery, channel mix can create economic pressure unless higher volume and operational efficiencies compensate for the lower margin profile.
4. Renewal rates vary by channel and market maturity
Worldwide renewal was 89.8%, below the 92.3% rate in the U.S. and Canada. Costco notes that newer international markets and a higher penetration of memberships sold online negatively affect worldwide renewal because online-acquired members renew at a slightly lower rate on average. Faster digital acquisition can therefore dilute this important loyalty metric.
5. Complex global operating footprint
Costco operates warehouses across numerous countries, eight national e-commerce markets, extensive logistics facilities and multiple ancillary businesses. This scale creates exposure to currencies, regulation, suppliers, labor, technology and local market differences. Maintaining Costco’s consistent price, quality and service proposition becomes operationally more demanding as the network expands.
For the broader external environment shaping these opportunities and risks, read our Costco PESTEL Analysis 2026.
Opportunities
1. Continued warehouse expansion
Costco added 24 net new warehouses during fiscal 2025 and ended the year with 914 locations. New warehouses can add members, sales and geographic convenience. International markets offer additional runway because Costco’s network remains far smaller outside North America, although successful expansion requires adaptation to local real-estate, consumer and regulatory conditions.
2. Higher Kirkland Signature penetration
Costco explicitly expects to continue increasing private-label sales penetration. Kirkland Signature can provide high quality at prices generally below national brands while usually earning higher margins. Greater penetration can therefore reinforce the value proposition, differentiate the assortment and support gross economics without relying primarily on higher member-facing prices.
3. Digital and e-commerce growth
E-commerce represented approximately 7% of net sales in 2025 and comparable e-commerce sales increased 16%. Digital channels can broaden assortment, increase convenience and attract new members. Continued improvement in logistics, delivery and digital engagement could increase the share of member spending captured by Costco even when purchases occur outside a warehouse.
4. Membership base and Executive penetration
Costco states that growth in its membership base, higher Executive membership penetration and sustained renewal materially influence profitability. Warehouse expansion and digital acquisition can add members, while the Executive 2% reward can encourage qualified spending. The 2024 fee increase also demonstrates the recurring-revenue opportunity embedded in a loyal membership base.
5. International operating leverage
Other International net sales increased 8% in 2025, while comparable sales excluding currency and gasoline effects increased 8%. As international warehouse cohorts mature, Costco has an opportunity to build stronger renewal, purchasing scale and local operating leverage. A broader geographic mix could also gradually reduce dependence on the U.S. market.
Threats
1. Intense retail and e-commerce competition
Costco describes competition as vigorous and widespread across global, national and regional wholesalers and retailers, including e-commerce operators. Competitors can challenge Costco on price, convenience, assortment, delivery speed or service. Because Costco’s proposition depends on visible member savings, sustained competitive price pressure can constrain its ability to expand merchandise margins.
2. Inflation, tariffs and merchandise cost pressure
Costco’s low-markup model can be pressured by rising merchandise, labor, freight or other operating costs. Tariffs and trade-policy changes can also affect imported products. Passing higher costs to members may weaken perceived value, while absorbing them can reduce gross margin, forcing Costco to balance near-term economics against long-term member loyalty.
3. Foreign-currency volatility
Currency movements reduced fiscal 2025 net sales by approximately $1.94 billion and net income by $97 million. As Costco expands internationally, reported results become more exposed to exchange rates. Currency can obscure underlying operating growth and affect the translated economics of Canadian and Other International operations.
4. Cybersecurity and technology disruption
Costco depends on information systems for transactions, e-commerce, membership, supply chains and other operations. Its Form 10-K identifies cybersecurity risk and notes that controls cannot guarantee protection. A material incident could interrupt sales, compromise information, increase remediation costs and damage member trust in a business built on recurring relationships.
5. Kirkland Signature quality or supply failures
Kirkland is increasingly important to differentiation and margin. Costco states that maintaining consistent quality, competitive pricing and availability is essential to member loyalty. A significant product-quality issue, supply interruption or loss of member confidence could therefore affect both merchandise sales and the broader perception of Costco’s value proposition.
Costco’s strengths also reinforce one another. The membership requirement creates a known customer base; high renewal supports recurring fee income; strong traffic creates purchasing scale; purchasing scale supports low prices; and low prices reinforce renewal. This flywheel is difficult to separate into individual advantages because the system’s value comes from the interaction among them.
Its weaknesses are similarly connected to the model. Thin merchandise margins make cost control important, while rapid growth adds warehouses, employees, suppliers and technology dependencies. International and digital expansion can increase addressable demand but also add currencies, regulation, fulfillment expense and lower-renewing online-acquired membership cohorts.
Costco’s 2025 operating data nevertheless show significant resilience. Core merchandise sales increased $19.09 billion, or 10%, across all categories. Gross margin percentage increased 20 basis points, and operating cash flow rose by nearly $2.0 billion. These figures provide financial capacity to pursue warehouse and digital opportunities while absorbing some volatility in fuel, currency and merchandise costs.
The central strategic tension is preserving member value while scaling. Costco’s filing repeatedly links profitability to comparable sales and membership economics rather than aggressive product markups. Opportunities that strengthen traffic, renewal, private-label penetration or network productivity fit naturally with this model; threats become most serious when they weaken the price-value perception, merchandise availability or member trust that sustain renewal.
Costco’s 2025 results also show that headline revenue can be affected by factors outside core merchandising execution. Lower gasoline prices reduced net sales by $2.33 billion, and currency movements reduced sales by approximately $1.94 billion. Yet comparable sales excluding gasoline and currency effects increased 8% companywide. This distinction strengthens the case for evaluating Costco through member activity and underlying comparable performance, while also highlighting its exposure to fuel and foreign-exchange volatility.
Overall, Costco’s SWOT profile is tightly linked to the durability of its membership flywheel. The same scale that creates purchasing power also increases operational exposure, making disciplined execution essential.
The durability of member loyalty remains the key variable connecting Costco’s principal strengths, weaknesses, opportunities and threats.
Source: Costco Wholesale Corporation, FY2025 Annual Report / Form 10-K.