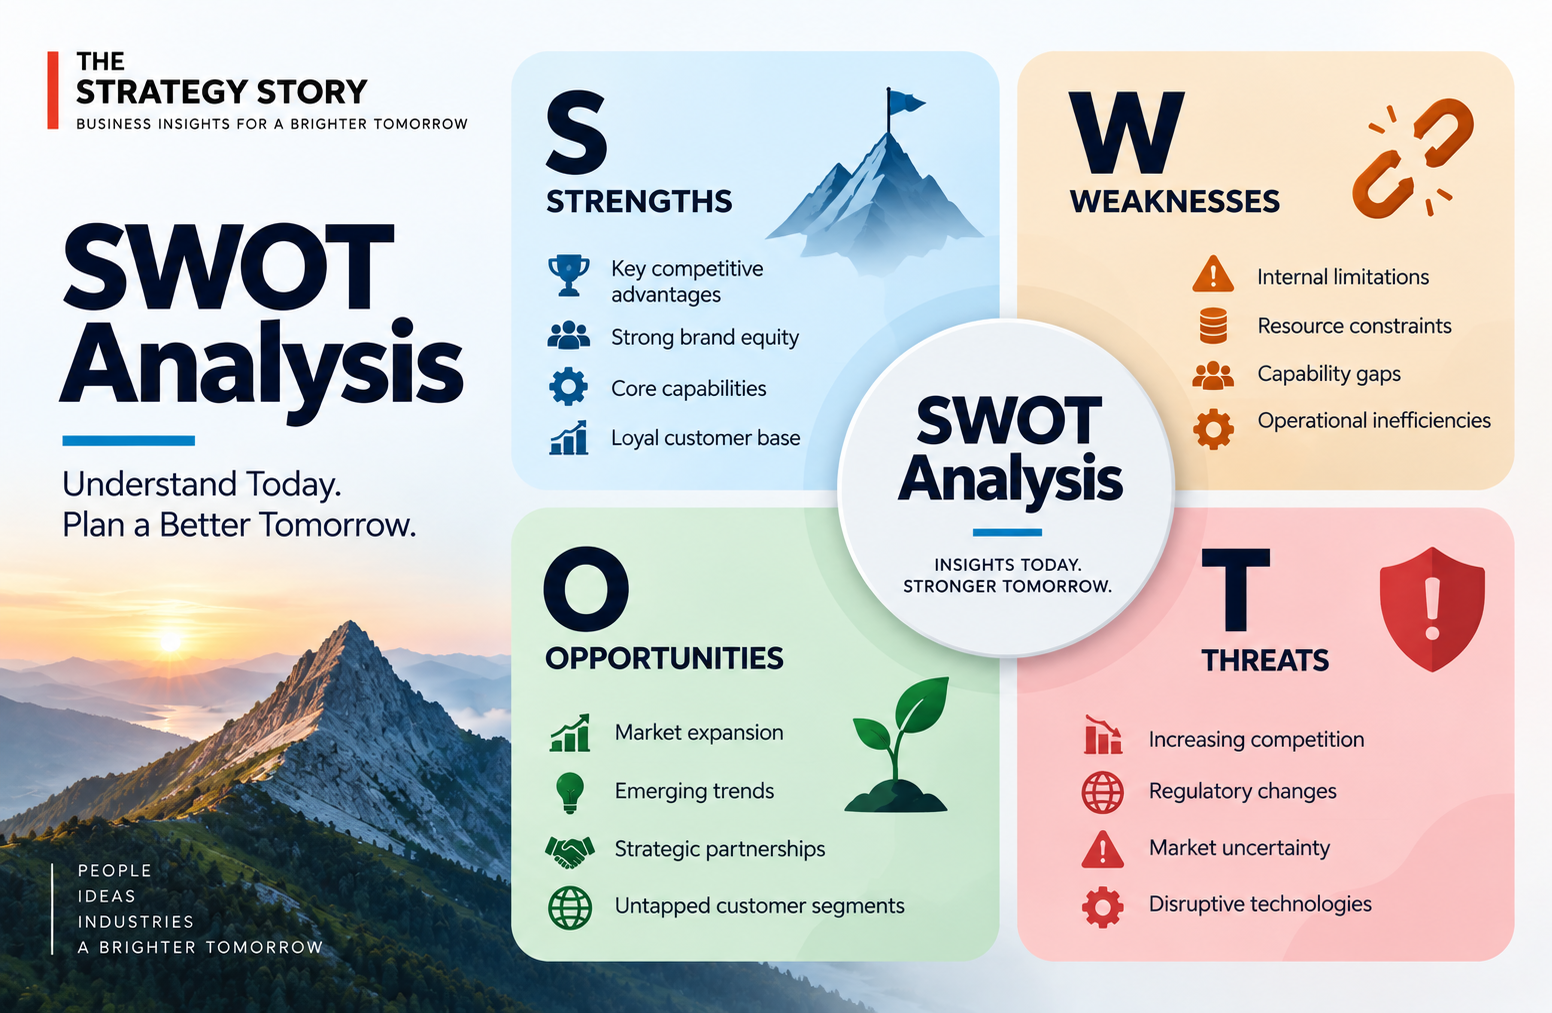
Wells Fargo enters 2026 with approximately $2.1 trillion of assets, a $1.4 trillion deposit base and improving profitability. Yet the bank remains exposed to credit cycles, interest-rate changes, regulatory requirements and operational risk. This SWOT is based only on Wells Fargo’s 2025 Annual Report and Form 10-K.
Strengths
1. Large U.S. banking franchise
Wells Fargo was the fourth-largest U.S. bank holding company by assets at year-end 2025, giving it significant customer reach and operating scale. See our Wells Fargo Business Strategy 2026.
2. $1.4 trillion deposit base
Deposits provide a large funding base for lending and securities activities and create opportunities to deepen consumer and commercial relationships.
3. Diversified operating segments
Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth and Investment Management diversify the sources of revenue.
4. Improving profitability
2025 net income rose 8% to $21.3 billion, EPS increased to $6.26 and ROTCE improved to 14.6%.
5. Strong mix of interest and fee revenue
Wells Fargo generated $47.48 billion of net interest income and $36.22 billion of noninterest income. The model is detailed in our Wells Fargo Business Model 2026.
Weaknesses
1. High operating-cost base
Noninterest expense was $54.84 billion and the efficiency ratio remained 66%, leaving meaningful room for productivity improvement.
2. Regulatory complexity
Wells Fargo’s size and business breadth require extensive risk, compliance and control infrastructure, raising fixed costs and management complexity.
3. Credit-cycle exposure
Nearly $1 trillion of loans creates material sensitivity to borrower health and economic conditions.
4. Rising nonperforming assets
NPAs increased to $8.5 billion, or 0.86% of loans, driven by higher commercial and industrial nonaccrual loans.
5. Interest-rate sensitivity
Net interest income depends on asset yields, deposit pricing and funding mix, making earnings sensitive to changing rates and customer behavior.
Opportunities
1. Expand Corporate and Investment Banking
Wells Fargo can deepen corporate relationships by combining lending with treasury, underwriting, advisory and markets services.
2. Grow Wealth and Investment Management
Wealth and brokerage relationships can increase recurring fee income and broaden the economics of affluent customer relationships.
3. Improve efficiency
Digitalization, process redesign and organizational simplification can improve the 66% efficiency ratio if executed without weakening controls.
4. Cross-business relationship growth
The breadth of Wells Fargo’s products creates opportunities to serve more needs of existing consumer and commercial customers.
5. More balanced revenue mix
Noninterest income grew 5% in 2025. Further fee growth can reduce reliance on net interest income and loan growth.
Threats
1. Regulatory changes
Capital, liquidity, consumer-protection and supervisory rules can raise costs or constrain growth. See our Wells Fargo PESTEL Analysis 2026.
2. Credit deterioration
Economic weakness can increase delinquencies, charge-offs and provisions across consumer and commercial portfolios.
3. Deposit competition
Customers can shift deposits toward higher-yielding alternatives, increasing funding costs and pressuring net interest margins.
4. Cybersecurity and fraud
Digital banking exposes Wells Fargo to cyberattacks, fraud and operational disruptions that can create financial and reputational damage.
5. Competition from banks and nonbanks
Wells Fargo competes across deposits, lending, payments, investment banking and wealth management against large banks, fintechs and specialized financial firms.
Source: Wells Fargo, 2025 Annual Report / Form 10-K.