
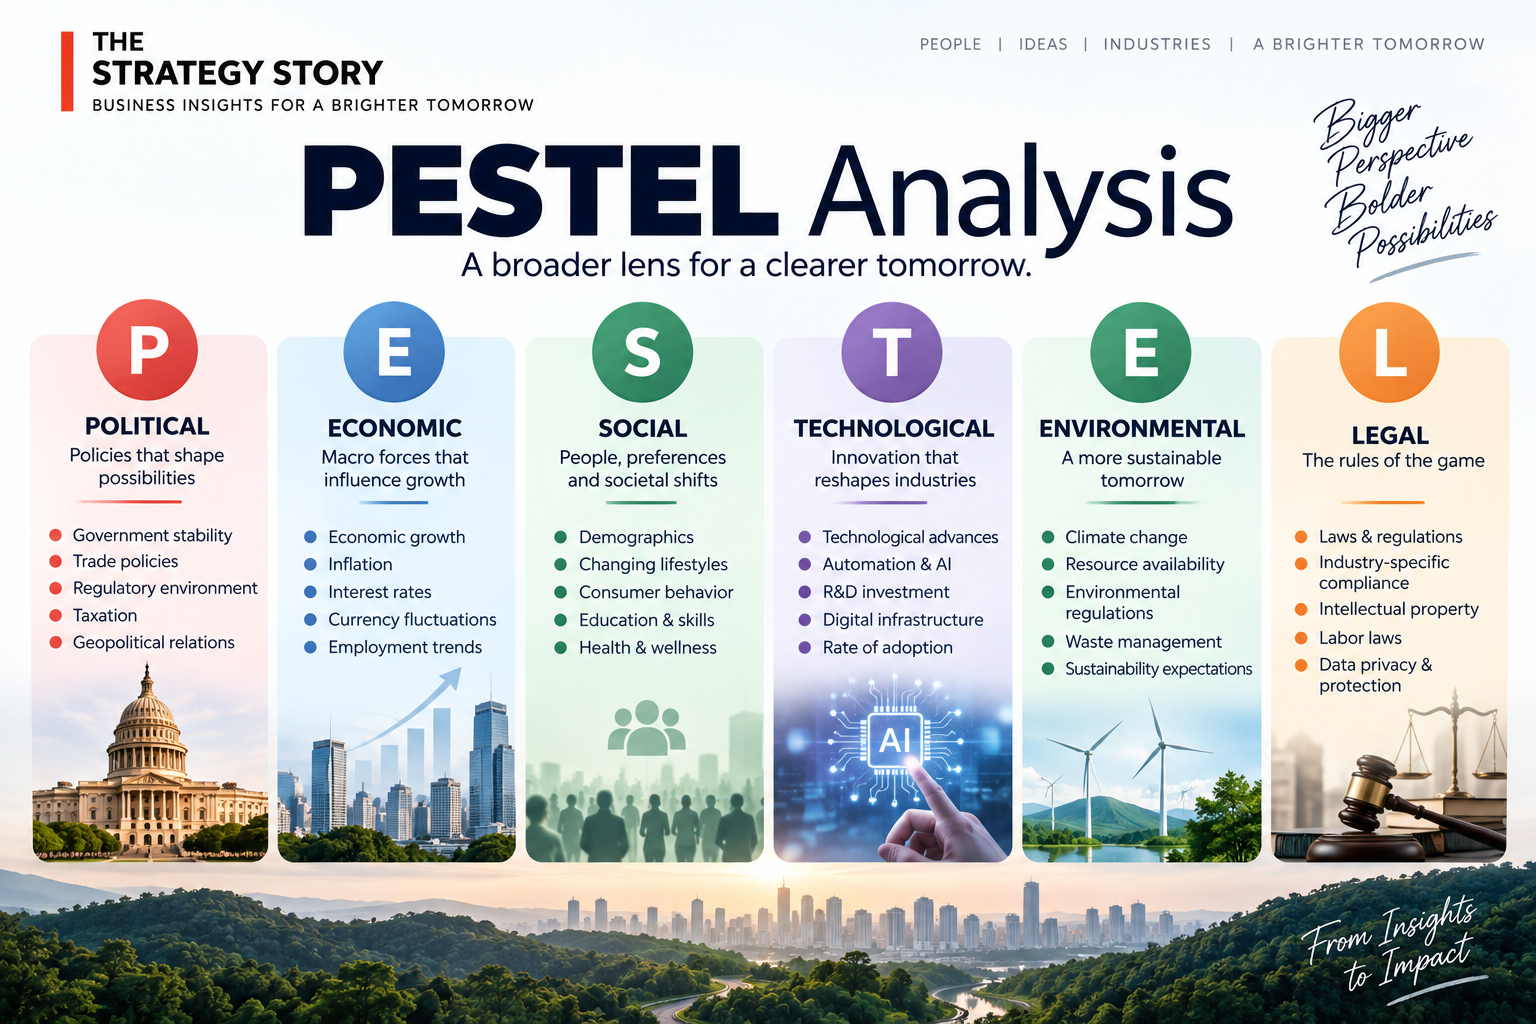
Wells Fargo operates in an environment where monetary policy, regulation, technology and consumer financial health directly shape profitability. With approximately $2.1 trillion of assets, $986.2 billion of loans and $1.4 trillion of deposits at year-end 2025, relatively small external changes can have large financial effects. This PESTEL uses only Wells Fargo’s 2025 Annual Report and Form 10-K.
Political Factors
1. Banking regulation
Federal and state regulators influence Wells Fargo’s capital, liquidity, consumer practices, acquisitions and permissible activities.
2. Capital-policy changes
Changes to risk-based capital requirements can affect how much lending and other balance-sheet activity Wells Fargo can support.
3. Consumer-protection policy
Rules governing mortgages, cards, deposits and other retail products can change pricing, disclosures, servicing and compliance costs.
4. Fiscal and trade policy
Government policies can affect economic growth, business confidence, inflation and borrower performance, indirectly influencing credit demand and losses.
5. Supervisory expectations
Large banks face intensive supervision of governance and controls. These constraints are explored in our Wells Fargo SWOT Analysis 2026.
Economic Factors
1. Interest rates
Rates influence asset yields, deposit costs and customer behavior. Net interest income was $47.48 billion in 2025, making rate dynamics central to earnings.
2. Credit conditions
Provision for credit losses was $3.66 billion while nonperforming assets reached $8.5 billion. Economic weakness can materially raise credit costs.
3. Employment and consumer health
Household income and employment affect deposits, card spending, mortgage performance and consumer loan losses.
4. Commercial activity
Business investment and transaction activity affect commercial lending, treasury services and Corporate and Investment Banking revenues.
5. Asset markets
Equity and bond markets influence investment-banking activity and wealth-management fees. The revenue architecture is explained in our Wells Fargo Business Model 2026.
Social Factors
1. Shift toward digital banking
Customers increasingly expect convenient digital access alongside secure and reliable financial services.
2. Trust in financial institutions
Banking relationships depend on customers believing deposits, data and transactions will be handled responsibly and reliably.
3. Homeownership and housing behavior
Housing affordability, mobility and consumer preferences affect mortgage origination, servicing and home-lending demand.
4. Small-business financial needs
Small businesses require deposits, payments and credit, creating opportunities to deepen relationships across multiple banking products.
5. Wealth accumulation
Growth in household wealth can increase demand for brokerage, investment advice and wealth-management services.
Technological Factors
1. Digital banking platforms
Technology increasingly determines customer experience, service costs and competitive differentiation in consumer and commercial banking.
2. Cybersecurity
Wells Fargo must protect customer data, payment systems and critical infrastructure from increasingly sophisticated attacks.
3. AI and automation
Automation can improve productivity, fraud detection and customer service but introduces model, governance and operational risks.
4. Payments innovation
Faster digital payment methods can alter transaction economics and intensify competition from technology companies and fintechs.
5. Data and analytics
Better data can improve underwriting, personalization and risk management, supporting the efficiency and relationship strategy described in our Wells Fargo Business Strategy 2026.
Environmental Factors
1. Physical climate risks
Severe weather can damage collateral, disrupt customers and affect loan performance in exposed regions.
2. Real-estate collateral exposure
Environmental events can affect property values and insurance availability, influencing mortgage and commercial-real-estate credit risk.
3. Business continuity
Natural disasters can disrupt branches, data infrastructure, employees and customers, requiring resilient operations.
4. Environmental regulation of clients
Changes affecting corporate borrowers can alter their cash flows, investment needs and credit quality, indirectly affecting the bank.
5. Environmental disclosure requirements
Large financial institutions may face evolving disclosure and risk-management expectations; the annual report supports treating this as a compliance consideration rather than attributing a specific revenue effect.
Legal Factors
1. Consumer financial law
Wells Fargo is subject to extensive rules covering lending, servicing, deposits, cards and customer disclosures.
2. Capital and liquidity rules
Legal requirements determine minimum buffers and influence dividends, repurchases and balance-sheet growth.
3. Litigation and enforcement
Banking activities can generate private litigation, regulatory investigations, penalties and remediation costs.
4. Privacy and data law
Handling large volumes of financial and personal information creates significant data-protection obligations.
5. Anti-money-laundering requirements
Wells Fargo must maintain systems to detect and prevent illicit financial activity, creating substantial compliance and technology requirements.
Source: Wells Fargo, 2025 Annual Report / Form 10-K.