
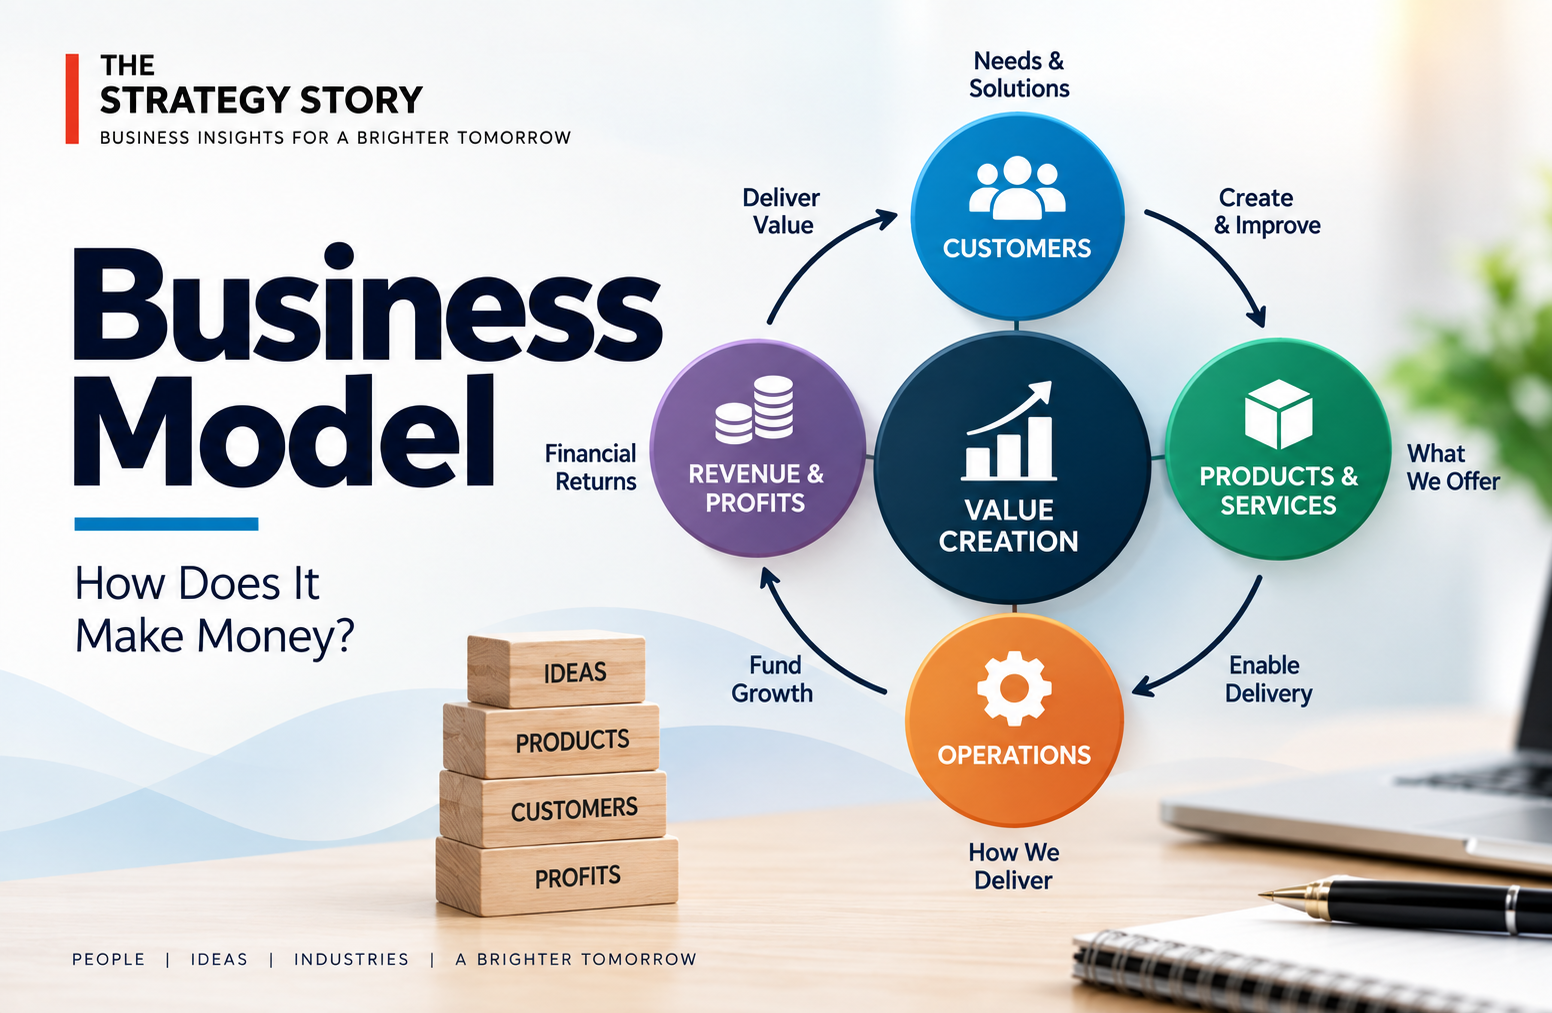
Arista Networks builds high-speed, data-driven networking platforms for large AI, data center, campus and routing environments. Its business model combines networking hardware with the EOS software platform, network applications and recurring support services. In 2025, revenue surged 28.6% to $9.01 billion while net income reached $3.51 billion, demonstrating an unusual combination of high growth and high profitability.
Industry Problem Arista Networks Solves
Modern cloud and AI infrastructure must move enormous volumes of data among servers, accelerators, storage systems and users with extremely low latency and high reliability. Traditional network architectures can become operationally complex as data centers scale to hundreds of thousands of endpoints and AI clusters require increasingly dense east-west traffic.
Arista addresses this with high-speed Ethernet switching and routing platforms controlled through a common software architecture. Its Extensible Operating System, or EOS, is designed to provide consistent operations across the portfolio, while CloudVision and related software help customers automate, monitor and manage networks at scale.
The strategic logic behind Arista’s expansion from cloud networking into AI and campus is explored in our Arista Networks Business Strategy 2026.
Arista Networks’ Unique Solution
Arista differentiates through a software-led architecture running across merchant-silicon-based networking platforms. Rather than maintaining different operating systems for different product families, EOS provides a common foundation. That consistency can reduce operational complexity and accelerate feature deployment across customer networks.
Arista’s portfolio spans data center and cloud networking, AI networking, routing and cognitive campus environments. The company also offers network management, telemetry, security and automation capabilities. This broadening portfolio allows Arista to address more of a customer’s network while retaining a unified software model.
The concentration and competitive risks within this model are examined in our Arista Networks SWOT Analysis 2026.
Arista Networks Business Model
High-performance networking products
Product revenue was $7.58 billion in 2025, up from $5.88 billion in 2024 and representing roughly 84% of total revenue. Arista sells switching and routing systems used in large-scale data centers, AI clusters, campus networks and other high-performance environments. Product growth is driven by customer deployments, higher network speeds and expansion into adjacent networking use cases.
Software as a strategic control layer
EOS is embedded across Arista’s networking portfolio and provides programmability, automation and operational consistency. Software strengthens hardware economics because customers are not selecting only a switch; they are adopting an operating architecture that can span a larger network footprint.
Services and support
Service revenue increased to $1.43 billion in 2025 from $1.12 billion in 2024, or about 16% of total revenue. Support and services provide a recurring component that grows alongside the installed base and deepens long-term customer relationships.
Customer and channel model
Arista sells through direct sales and channel partners to large cloud companies, enterprises and service providers. Large customers can represent significant portions of revenue, creating both powerful growth opportunities and concentration risk.
The regulatory, geopolitical and supply-chain factors shaping this model are covered in our Arista Networks PESTEL Analysis 2026.
How Does Arista Networks Make Money?
The company primarily monetizes the sale of networking products. In 2025, product revenue accounted for $7.58 billion of $9.01 billion total revenue. Service revenue contributed another $1.43 billion through support and related offerings associated with deployed infrastructure.
The economic attractiveness is visible in gross profit. Arista generated $5.77 billion of gross profit in 2025, producing a gross margin of approximately 64.1%, essentially unchanged from 2024 despite rapid revenue expansion. This suggests the company scaled without sacrificing its overall gross-margin structure.
Operating leverage is even more striking. Operating income rose to $3.86 billion from $2.94 billion, while total operating expenses increased to $1.91 billion. R&D remained the largest operating investment at $1.24 billion, showing that Arista reinvests heavily in technology while preserving substantial profitability.
Arista Networks Financial Analysis
Revenue increased 28.6% from $7.00 billion in 2024 to $9.01 billion in 2025. Product revenue rose approximately 28.8%, while service revenue increased approximately 27.7%. Growth was therefore broad across both the initial product sale and the recurring installed-base service stream.
Net income reached $3.51 billion, up 23.1% from $2.85 billion. Operating income increased roughly 31% to $3.86 billion. The faster growth in operating income than revenue demonstrates operating leverage even as R&D spending increased 24% to $1.24 billion.
The company also maintains substantial liquidity and investment resources, which gives it flexibility to fund inventory, R&D, acquisitions and capacity commitments. However, networking supply chains require long lead times and commitments, so working-capital management remains important. Inventories increased during 2025 as Arista supported higher demand and supply resilience.
Customer concentration remains a structural feature. Large cloud and AI customers can drive exceptional growth but also make quarterly and annual results sensitive to deployment timing and purchasing decisions.
Future of Arista Networks’ Business Model
AI networking is becoming a major extension of Arista’s cloud heritage. AI clusters require high-bandwidth connections among accelerators, and Ethernet is evolving to serve these workloads. Arista’s opportunity is to make Ethernet a preferred scale-out and scale-up networking architecture for AI infrastructure while preserving its software differentiation.
Campus networking creates a second expansion vector. Arista can take its EOS-based operating model beyond data centers into enterprise switching, wireless and network management, increasing the addressable wallet within existing and new customers.
The business model therefore has three reinforcing engines: high-performance hardware drives initial deployments; EOS and network software increase differentiation and operational stickiness; and support services monetize the growing installed base. If AI and campus continue expanding, Arista can diversify beyond its historical cloud concentration while retaining the architecture that produced its strong margins.
The central challenge is sustaining innovation as network speeds and AI architectures evolve rapidly. Arista’s 2025 results show that it can grow above 25% while maintaining a 64.1% gross margin. The durability of that combination will depend on technology leadership, customer diversification and disciplined supply-chain execution.
Source: Arista Networks, 2025 Annual Report / Form 10-K.