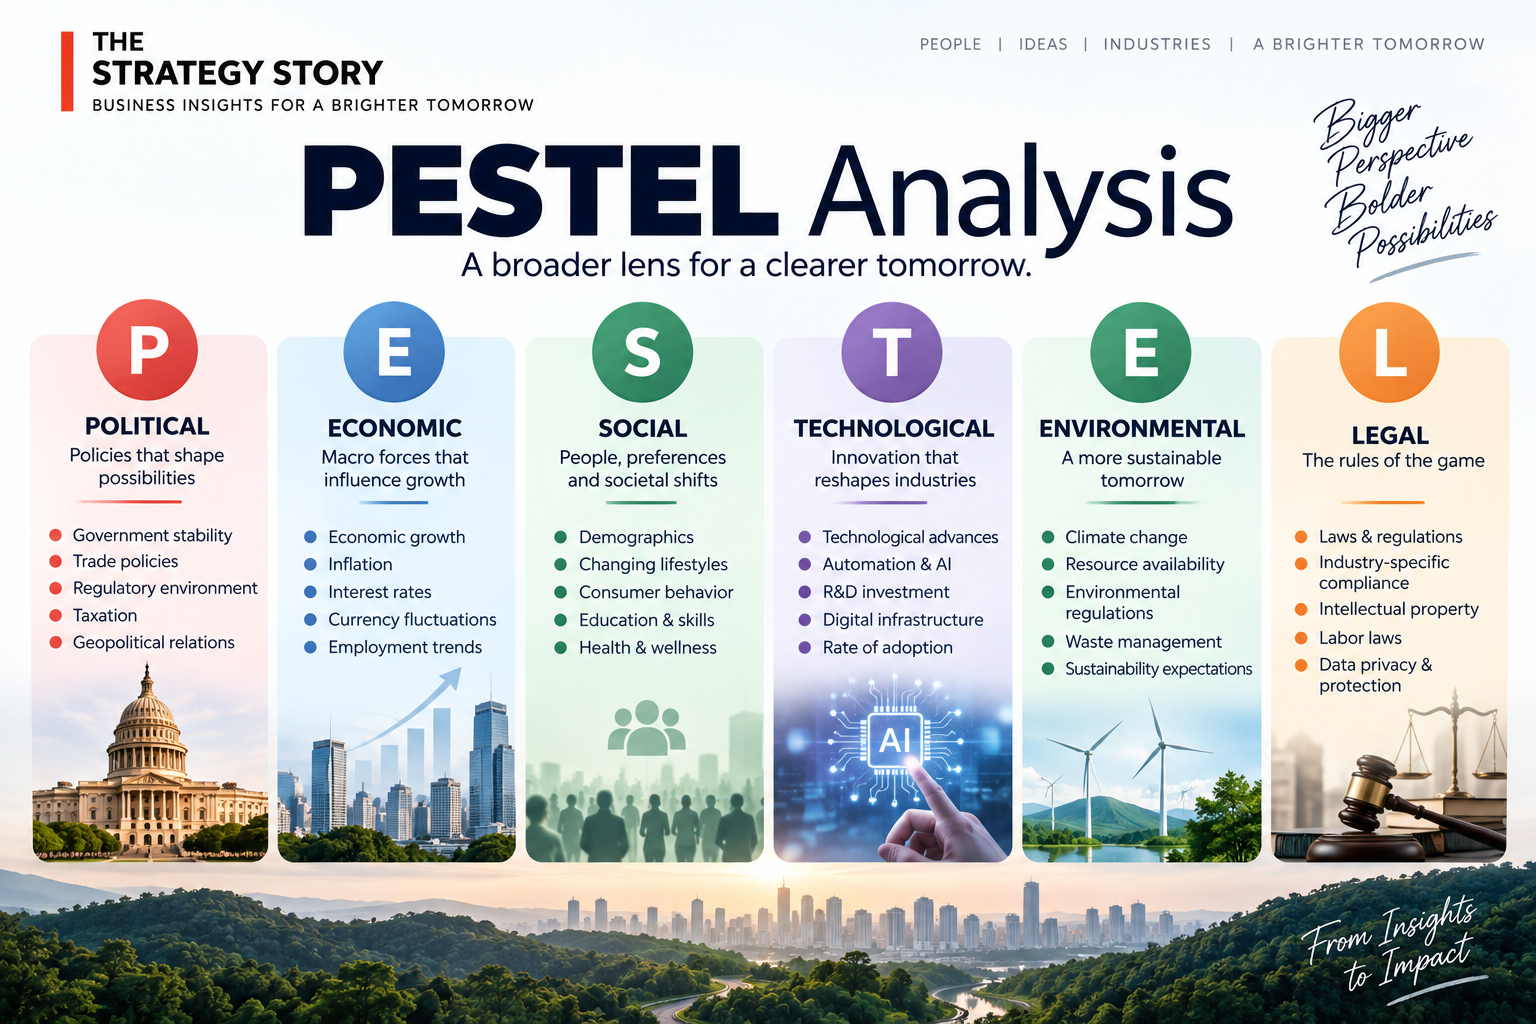
Bank of America operates at the center of the U.S. and global financial system, making its external environment unusually important. Monetary and fiscal policy affect rates and credit demand; technology reshapes distribution; regulation influences capital and product economics; and social expectations determine how clients choose and use financial services.
For the economics of the franchise, read our Bank of America Business Model 2026.
Political Factors
1. Banking regulation
Government and regulatory policy influences capital, liquidity, lending and consumer practices. Large-bank rules can materially affect how Bank of America allocates its balance sheet.
2. Fiscal policy
Government spending and taxation influence economic activity, borrowing needs and financial markets, indirectly affecting consumer and corporate banking demand.
3. Geopolitical risk
Bank of America serves clients across more than 35 countries and jurisdictions. Sanctions, conflict and political instability can affect markets, client activity and compliance requirements.
4. Consumer-finance policy
Rules covering fees, credit, disclosures and fair treatment influence product economics and operating processes across the large consumer franchise.
5. Capital-market policy
Rules affecting securities markets, underwriting and trading can influence Global Banking and Global Markets revenue and the cost of compliance.
For management’s response, see our Bank of America Business Strategy 2026.
Economic Factors
1. Interest rates
Rates influence loan yields, securities income, deposit pricing and customer behavior. The shape and speed of rate changes can materially affect net interest income.
2. Credit cycle
Employment, corporate profitability and asset prices affect borrowers’ ability to repay. Economic weakness can increase delinquencies and credit losses across consumer and commercial portfolios.
3. Deposit competition
Higher market yields can encourage customers to move money toward alternatives. Banks may need to pay more to retain deposits, increasing funding costs.
4. Capital-market activity
M&A, debt and equity issuance, trading volumes and volatility influence investment-banking and markets revenue. Activity often changes with economic confidence and financing conditions.
5. Wealth and asset values
Market levels affect client wealth and asset-based fees. Strong markets can support wealth-management revenue, while declines can reduce fees and investor activity.
Social Factors
For a consolidated view of strengths and risks, read our Bank of America SWOT Analysis 2026.
1. Shift toward mobile banking
Approximately 41 million active mobile users demonstrate consumer preference for digital access. Customers increasingly expect banking to be immediate, intuitive and available continuously.
2. Demand for financial advice
Complex retirement, investment and borrowing decisions sustain demand for advice even as routine transactions become digital. This supports Merrill and branch-based advisory relationships.
3. Changing branch behavior
Customers perform fewer basic transactions in branches but may still value physical locations for advice and complex needs. Bank of America must continually optimize its network.
4. Trust in financial institutions
Customers entrust banks with money and sensitive information. Service failures, misconduct or security incidents can quickly weaken trust and increase customer attrition.
5. Demographic wealth transfer
Intergenerational transfer of assets creates both opportunity and retention risk for wealth managers. Merrill must build relationships with heirs as well as existing clients.
Technological Factors
1. Artificial intelligence
AI can improve service, employee productivity, fraud detection and analytical workflows. Banking applications require governance because mistakes can have financial and regulatory consequences.
2. Mobile and digital platforms
Digital infrastructure is now a core distribution channel. Reliability, speed and ease of use influence customer satisfaction and the economics of servicing millions of accounts.
3. Cybersecurity
Financial institutions are high-value targets for cyberattacks. Protecting customer data, payments and critical systems requires continuous investment and operational resilience.
4. Payments innovation
Real-time payments and digital wallets change how consumers and businesses move money. Bank of America must integrate new capabilities while maintaining security and compliance.
5. Data analytics
Large transaction datasets can improve fraud detection, service and risk management. Privacy, fair-lending and model-governance requirements constrain how data can be used.
Environmental Factors
1. Physical risks to borrowers
Severe weather and other physical risks can affect homes, businesses and collateral, influencing credit performance and insurance availability in exposed regions.
2. Operational resilience
Branches, offices and data infrastructure can face weather-related disruption. Business-continuity planning is necessary to maintain access to critical financial services.
3. Energy-sector financing
Changes in energy markets can affect corporate clients, project financing and credit exposures. The bank must assess risks within its lending and capital-markets activities.
4. Client transition risks
Policy, technology and market changes can alter the economics of client industries. These shifts can affect borrower creditworthiness and investment opportunities.
5. Resource efficiency
A large physical and technology footprint consumes energy and resources. Efficiency initiatives can reduce operating costs as well as environmental impact.
Legal Factors
1. Capital and liquidity requirements
Legal and regulatory frameworks determine minimum capital and liquidity buffers. Changes can materially affect balance-sheet capacity and returns.
2. Consumer-protection laws
Rules governing lending, fees, disclosures and fair treatment shape products and servicing across tens of millions of consumer relationships.
3. Anti-money-laundering obligations
Global banking requires extensive controls to identify customers, monitor transactions and comply with sanctions and financial-crime rules.
4. Privacy regulation
Bank of America holds sensitive financial data. Privacy laws influence how information is collected, shared, stored and used across digital and analytical systems.
5. Litigation and enforcement risk
Large financial institutions can face private litigation and regulatory enforcement across many activities. Failures can generate monetary penalties, remediation costs and reputational damage.
These PESTEL forces interact strongly in banking. Central-bank policy changes rates; rates influence deposits, lending and asset values; economic conditions affect credit; regulation determines capital requirements; and technology changes how customers move money. Bank of America therefore manages external factors as an interconnected system.
Monetary policy is particularly important. A change in short-term rates can reprice some assets and liabilities at different speeds. Profitability depends not simply on whether rates rise or fall but on the timing, mix and customer response across the balance sheet.
Inflation can influence the bank indirectly through both rates and borrower finances. Higher living or business costs may pressure some borrowers, while monetary-policy responses change funding and lending economics. The effect can vary significantly across consumer and commercial portfolios.
Employment is another key economic variable. Stable employment supports consumer credit performance and deposit activity, whereas job losses can increase delinquencies and reduce spending. Commercial borrowers are affected through demand, labor costs and profitability.
Social expectations increasingly center on seamless digital service. Customers compare banking apps not only with other banks but with leading consumer technology experiences. Slow or complex digital journeys can therefore weaken satisfaction even when core financial products remain competitive.
At the same time, financial decisions can require trust and advice. Mortgages, retirement planning and business financing are less routine than checking a balance. This supports a hybrid model in which technology handles simple activity and specialists focus on complex needs.
Technology also changes fraud patterns. Faster digital payments improve convenience but can accelerate the movement of fraudulent funds. Banks need real-time detection and authentication capabilities that evolve alongside new payment methods.
Operational resilience extends beyond cybersecurity. Cloud services, telecommunications, data centers and third-party technology providers can all become points of failure. Bank of America must manage dependencies across a complex technology supply chain.
Environmental risks can translate into traditional banking risks. Damage to collateral may increase loss severity, while changing insurance availability can affect property economics. Corporate transition risks can influence the creditworthiness of businesses in exposed industries.
Legal obligations around fair lending and consumer treatment become more complex as analytics and AI expand. A model can improve efficiency but still create legal risk if outcomes are discriminatory or explanations are inadequate. Governance must evolve with technology.
Financial-crime regulation also becomes more demanding as payments become faster and more global. Anti-money-laundering and sanctions systems need to identify suspicious activity without unnecessarily disrupting legitimate customer transactions.
For 2026, Bank of America’s external environment remains defined by the need to adapt without compromising resilience. Digital innovation, changing rates and evolving regulation create opportunities, but the bank’s scale means failures in controls can carry unusually large consequences.
Fiscal policy can influence corporate borrowing and household finances through government spending, taxation and deficits. It can also affect bond markets and interest rates, linking political decisions to the value and funding of bank balance sheets.
Geopolitical events can influence market volatility as well as direct compliance obligations. Global corporate clients may need currency, liquidity and risk-management support when trade routes, sanctions or supply chains change, creating both client demand and operational complexity.
Economic growth affects the bank through volume as well as credit quality. Expanding businesses may borrow and invest more, while households may spend and purchase homes. Weak growth can reduce these activities before credit losses become visible.
Housing markets are particularly relevant to consumer banking. Home prices, mortgage rates and transaction volumes influence mortgage demand and collateral values. Regional differences can produce divergent outcomes within the national portfolio.
Wealth inequality and access to financial services create social and regulatory considerations. Banks face expectations to serve diverse communities fairly while maintaining prudent underwriting. Product design and distribution need to balance inclusion with credit risk.
Customer expectations around fraud protection are also rising. Consumers often expect banks to identify suspicious activity quickly while allowing legitimate payments to move without friction. Achieving both requires increasingly sophisticated analytics and authentication.
Open banking and data-sharing developments can change competition by making it easier for customers to connect financial information across providers. This may reduce switching barriers while also enabling Bank of America to integrate external data into customer experiences where permitted.
Third-party technology risk is another growing factor. Banks rely on vendors for software, infrastructure and specialized services. Regulation increasingly expects institutions to manage these dependencies as carefully as internally operated systems.
Physical climate risks may also affect geographic concentration. If insurance becomes more expensive or unavailable in exposed property markets, collateral values and borrower affordability can be affected. Credit models may need to incorporate these changing conditions.
Environmental transition can create financing opportunities alongside risks. Companies investing in new infrastructure or adapting business models may require capital, advisory and risk-management services. Bank of America must assess opportunities within its credit and market-risk frameworks.
Legal requirements increasingly extend to model governance. As banks use advanced analytics and AI, regulators may expect evidence that models are accurate, explainable and appropriately monitored. Poor governance can turn technological innovation into compliance exposure.
Finally, capital rules can influence competitive behavior. Higher required capital raises the cost of balance-sheet-intensive activities and may shift some financing toward nonbank institutions. Bank of America must decide which businesses still generate adequate returns after regulatory capital charges.
Source: Bank of America Corporation, 2025 Annual Report / Form 10-K.